THE PERFECT HOME TRADING SETUP

The Perfect Home Trading Setup: Our Top Tips

No doubt one of the most appealing aspects of pursuing a career as a forex trader is the fact that it can be done anywhere, at any time. All you really need is a laptop and an internet connection and away you go!


However, if you do really want to reach the dizzying heights of true success on the forex markets, paying close attention to your setup is definitely a wise idea, as your choice of working environment can make or break you where productivity is concerned. 


In fact, if you’ve been plateauing a bit of late, you may want to cast a critical eye around your surroundings to see if they could be having an impact on your mood and general outlook, something that we all know can have a significant knock-on effect where trading success is concerned.


Assuming that you do most of your work from home, it makes sense to design an at-home office that promotes productivity and clear-headed thinking so that you can help ensure strong decision-making, no matter what happens day in, day out.


To get it right, you’ll need to know who you are as a person and what sort of environments you like to work in. Do you, for example, thrive and perform at your best in total silence? If so, you might want to prioritise soundproofing of your space to ensure that there are no distractions from outside or elsewhere in the house.


Alternatively, if you know you need some background noise going on, installing a top-notch sound system that allows you to play your favourite music or stick on some white noise could help you concentrate and see the results you’re looking for far quicker. 


Other people, meanwhile, do well when there’s digital wallpaper playing in the background, so if this sounds like you, making sure that there’s a TV or some other kind of screen setup in place could help you perform better on the trading floor.


These are some of the more obvious suggestions, of course, but if you’re looking to go a bit deeper with your home office interior design ideas, here are just a few top tips from us to help you ensure you get it right from the outset. Which of these will you try first?


Lighting


One of the most important aspects of any interior design scheme is your lighting system and it’s something that you should factor in at the very beginning of your plans. Leaving it till last or as an afterthought inevitably means that it may well miss the mark and you might find it hard to see what you’re doing… and this can really have an impact on your performance.


If the lighting in your home office is poor, you run the risk of headaches and eye strain, neck, back and muscle strain, a dip in productivity, an increased risk of slips, trips and falls, and it can even have an impact on your mental health if you’re not careful.


A recent study by City University London found that while lighting on its own is unlikely to have a big impact on performance, it’s one of several factors that come together to create a healthy work environment, which can promote engagement, wellbeing and productivity. 


What’s more, even the colour of light you decide to go for can have an impact on your mood and work performance, so it’s certainly worth taking the time to experiment with different options to see what effect they can have.

A truth universally accepted, however, is that natural light is one of the best sources of light you can go for, having positive effects on your wellbeing… so putting your desk near a window could make a big difference to how well you trade over time.


Once you’ve worked out how to maximise the amount of daylight you can flood your space with, you’ll then need to think about general and task lighting. Think about what time of day you prefer to trade in, as this will affect what lighting would be most appropriate. If you’re a night-time trader, for example, you’ll need high-quality task lighting to help keep you alert.


Ergonomics


Spending long working hours sat at a desk in front of a computer screen can really take its toll on you physically, mentally and emotionally, so it’s essential that you factor ergonomics into your home office design scheme.


You might not think it but sitting incorrectly and not having the right setup can actually put you at risk of developing all sorts of musculoskeletal disorders, everything from chronic low back pain to repetitive strain injury and carpal tunnel syndrome, to name just three. 


Conditions like these can take a long time to resolve themselves, so it makes sense to focus on prevention rather than cure if you can.


There are lots of little ergonomic tricks of the trade you can employ that will help you keep chronic pain at bay, however, such as by making sure that the top of your computer screen is at or just below eye level so you don’t risk putting your neck in stressful positions.


When seated (on a comfortable chair that offers you proper lower back support), make sure that your elbows are close to your body and properly supported, with your wrists and hands in line with your forearms.


In terms of chair height, you need to make sure that you are able to keep your feet flat on the floor at all times, so make the necessary adjustments to help you achieve this.


Another option, of course, is a standing desk if you really don’t want to be sitting down for hours at a time. It seems that there are actually all sorts of health benefits associated with these desk options, everything from reducing your risk of weight gain to potentially reducing blood sugar levels, reduced risk of heart disease and a reduction in back pain.


Interior niceties


Injecting some of your personality into your at-home office is easily achievable, since you don’t have any managers to pander to and don’t have to worry about work-related branding. The design world is your oyster, so to speak!


Even if you’re not particularly confident in your design skills, you can easily put together a lovely scheme that helps you enjoy your working environment and gives your productivity a serious boost. 


And, failing that, you could always consider bringing in some professional help to ensure that you create a beautiful room that speaks to who you are while ensuring that you’re able to get the trading job done successfully.


Before you make any shopping decisions, however, it’s important to take the time to think about what you actually need in order to work effectively. If storage is an essential, for example, make sure that your choice of desk has lots of drawers, or that you’ve picked a part of the house that allows you to install tall shelving units.


Also consider how you can create a happy and healthy workspace through interior design choices. It’s long been known that proximity to nature has a big impact on our overall mood and this is something you can easily tap into for your home office. 


The good news is that it isn’t at all difficult to bring nature into the house… all you need is some plants here and there, an incredibly easy and quick decorating win.


Low-maintenance plants are perhaps a good idea, especially if you’re new to the wonderful world of growing, so you don’t have to worry that you won’t have the time to look after them. 


Picking plants that can look after themselves is a good place to begin – although you may well surprise yourself and find that you actually enjoy looking after the greenery, taking full advantage of the meditative effects of the practice.


But what plants to choose? Peace lilies are a great option for first-time plant owners as they don’t need lots of light and can come back relatively successfully if you accidentally overwater them. 


It’s also thought that they can help filter and purify the air (so great for your office and your health)… and they look beautiful to boot, with their stunning broad deep green leaves.


Something else that’s very easy to go and very attractive into the bargain is the dracaena. These mini trees are very popular and a truly striking addition to any part of the home. Pop your new plant somewhere with some bright but indirect light and give it some water when the top two inches of soil are dry. And that’s it! Job done!

Interested in finding out more about forex funding? Check out the programs we have on offer today.

Recent articles


Share:

HOW TO USE COLOUR TO BOOST YOUR TRADES

How To Use Colour To Boost Your Trades

Whether you’re just starting out on your forex trading journey or are old hat when it comes to trading currency pairs, one constant remains true… you will always be learning and finding new avenues of interest that could help you up your trading performance and continue raking in the big wins.


With trading, a lot of your success will depend on your mental and emotional health and wellbeing – and your overall outlook can have a huge impact on how well you do on the trading floor. 


This is why we blog so much about psychology and the importance of mindset… because it really can make all the difference between swim and sink if you’re looking to become a professional trader.


Interestingly, colour has the potential to have a significant impact on your mood and it can even potentially sway your decision-making, actions and behaviour (without you even knowing about it!), so researching colour psychology and how it can affect you could make a big difference where your trading prowess is concerned.


What is colour psychology?


At its core, colour psychology is simply the study of how different colours can influence human behaviour, with the various shades associated with their own connotations and potential psychological effects. 


There are cultural differences, of course, and you also need to consider personal preference, but there are typical associations that different colours generally have… such as red for danger, for example.


Psychologist Carl Jung even went so far as to suggest that people themselves could be sorted into four different colours based on their temperaments: Cool Blue, Earth Green, Sunshine Yellow and Fiery Red.


According to Jung, everyone has all these different colour energies within themselves but to varying degrees and the different energies will manifest themselves depending on what’s’ going on around us, although we do have one dominant colour energy that will affect us and our behaviour the most.


Fiery Red, for example, is associated with being positive, decisive, assertive and bold, while Sunshine Yellow denotes a cheerful, uplifting, enthusiastic and spirited side. Earth Green, meanwhile, suggests a soothing, calming and tranquil personality, while Cool Blue types remain analytical, detached and objective, demonstrating little to no bias.


For traders, adopting a more Cool Blue attitude to life could be particularly useful, since people with this type of dominant energy typically lead lives based on facts, logic and principles grounded in reality. 


They’re highly analytical and consider all the possibilities to ensure they don’t make any uninformed decisions and enjoy approaching tasks systematically… all of which are excellent attributes for a trader to have.


Fiery Red energy could also prove particularly useful for forex performance and these personality types are very action-focused, capable of making swift decisions without being swayed by past events. 


They prioritise focus and efficiency… although this can be detrimental to a certain extent if it leads to impatience and a need to exert control over any given situation.


How to use colour to boost productivity


If you accept the theory that colour can, indeed, affect your behaviour and emotions, it stands to reason that by surrounding yourself with certain shades you can actually exert some level of influence over your mental and emotional outlook, as well as your actions and reactions.


Taking the time to create an appropriate office or workspace at home or elsewhere is always advisable for traders and if you don’t have a robust setup in place, you may find that your trading success never quite hits the stratospheric heights you’d like it to.


You need to get your head in the game for trading and your work environment is essential for achieving this, so perhaps cast a critical eye over your office and see what changes you could introduce that could give you a big productivity boost.


To this end, armed with your new knowledge of colour psychology, you might want to consider doing a bit of painting, or surrounding yourself with home decor items in certain shades to help keep you in the right mindset for trading.


But what colours to go for? Which tones would be the most beneficial to use? 


Green


A great colour to consider if you’re looking to work efficiently and with intent focus is green. This is a restful and calming colour, known for helping to improve concentration, while boosting creativity and inspiring innovative thinking… so an ideal one for aspiring traders everywhere to go for.


Not only that, however, but green also has links to nature and the environment, which can help improve your mental, emotional and even physical health and wellbeing… something that will really help you be a resilient and successful trader. 


There’s a reason why biophilia really came to the fore as one of the top interior design trends during the pandemic (and why it hasn’t waned in popularity in the years since) and that’s because being connected to nature helps us to feel happier, less stressed, more creative and more productive.


Blue


If green doesn’t float your boat, or perhaps you want to bring in a range of different colours, you might find what you’re looking for with a blue design scheme.


Research from the University of Texas shows that this colour may have an important role to play in increasing productivity and, in fact, it was found that people seemed to work more effectively when their working environments were a combination of both blue and green… so it could prove to be a very winning combination indeed!


In terms of connotations, blue has long been associated with calmness, tranquility, peace and security, which could really help centre you as you trade, no matter whether you win or lose.


And like green, it too has links to the natural world, with blue the primary colour of the sea and sky, so you could feel even more connected to nature if you include it in your interior design ideas.


Red


The colour red is an interesting one because it is somewhat contradictory, representing love, passion, energy and excitement, but also anger and power… so it can yield positive and negative results, depending on how it’s used. 


If you do want to decorate your home office in this most energetic of colours, it would perhaps be wise to use it as an accent colour rather than painting all the walls in this shade, which could become overpowering quite quickly and start having a negative impact on your trades.


This interesting study, published back in 2017 by the Swedish House of Finance, looked into the effects that colour can have on investment behaviour, finding that when investors are faced with potential losses in the colour red, their risk taking is reduced. 


And when they’re shown past negative stock price paths in red, their expectations regarding future stock returns are reduced as well, consistent with the colour red being associated with avoidance behaviour. It was also found that red can reduce the propensity to buy stocks… all of which suggests you may want to be careful in your approach with this shade!


That all being said, warm colours like red are also very stimulating and can certainly give you a productivity boost if used in the right way.


Yellow


Another really energising colour to consider decorating with if you want to give your trades a boost is yellow. This shade radiates positivity and can really help keep your confidence levels high and your mood equally optimistic. 


A happy trader is usually a successful trader and yellow can really help invoke feelings of warmth and brightness, lifting your mood and keeping you focused on the road ahead, no matter what forks appear along the way.


However, as with red, you also need to be a bit careful when decorating with yellow as too much of it can be a bit wearing on the eyes and cause visual fatigue, so approach with caution. 


Again, you may want to avoid painting your walls in a bright yellow as, despite its cheerful nature, studies have shown that people are more likely to lose their tempers when in yellow rooms… and babies are even more likely to cry when their surroundings are yellow!


Grey


If you’re looking for a calming colour to decorate with, however, grey could very well be the way to go. 


Halfway between black and white, grey is associated with objectivity and neutrality – which could be absolutely perfect for traders, since it’s important to maintain an objective outlook when trading, not being swayed by your emotions no matter what happens on the trading floor. 


The formal aspect of the colour also represents clear-headed thinking and logic… exactly what you want to engender within yourself as a trader.


And from a purely design and style perspective, grey is an excellent choice because it goes well with a range of other colours because of its achromatic nature, so you’ll be able to pick out shades and tones easily, even if you’re not an experienced interior designer.

Interested in setting up your own funded forex trading account? Browse our site to find out more about the various programmes we have available.

Recent articles


Share:

HOW TO USE THE 80-20 RULE

How To Use The 80-20 Pareto Rule In Forex Trading

You may have heard of the Pareto rule, which is applied to many aspects of financial trading as well as other purposes. The basic idea is that 80% of outcomes are the result of 20% of the causes. Therefore, small changes can make a big difference to the end result of a process. This theory has been adopted by forex traders to improve their strategy.


Here’s a look in some more detail at the Pareto Principle, and how you can use it to strengthen your forex trading performance. 


Where does the Pareto Principle come from?

The idea is based on the observations of the Italian sociologist and economist Vilfredo Pareto (1848- 1923). He noted during the course of his studies that 80% of the land in Italy belonged to about 20% of the population. The story goes that this observation arose from noticing that 20% of the pea pods in his garden yielded 80% of the peas.


This led to the development of a power law distribution based around the 80/20 rule that has been applied to many other fields, particularly in the world of business and economics. In the 1940s, a management consultant named Dr. Joseph Juran applied the theory to quality control in factories.


He found that it held true for the proportion of defective products in relation to faults in the production process. In other words, 80% of the issues were caused by 20% of the flaws in the production method. Therefore, efforts to improve could be focused on one targeted area, which resulted in a great improvement in quality.  


However, it has been applied to areas as diverse as engineering, quality control, and healthcare. Another area the principle is commonly applied is occupational health and safety, which assumes that 20% of hazards are responsible for 80% of accidents and injuries. This allows safety experts to target their efforts in the areas where they will have maximum effect. 


In essence, the Pareto principle can reduce the time and effort spent trying to improve the many processes that matter only a little or not at all, and allow the work to be focussed on a much smaller area that will yield much greater benefits. It’s all about making the most efficient use of time, creativity, and resources.


 Investors often work to the rule that 20% of the holdings in a portfolio are responsible for 80% of the growth, and thus focus their attention on the most lucrative stocks and shares.


How can the Pareto Rule be applied to forex?

There is no one single way that the Pareto Rule is applied to forex trading, but the general concept that 20% of your efforts will reap 80% of the rewards is a useful principle to bear in mind. Here’s a look at some of the different ways that you can integrate this approach to your trading.


Trade less, trade better

Less is more, as the saying goes, and many forex traders abide by this principle. One of the most effective ways this is applied to forex trading is to concentrate on making fewer trades that are very well planned, rather than a greater number of trades that have had less preparation. 


Many new traders are keen to respond to every fluctuation in the market, rather than having the patience to wait until there is a worthwhile opportunity to make a good trade. More experienced traders develop the discipline not to trade when the market conditions are just not there. 


Some traders might even tell you that 80% of the time, the market is not worth trading, but 20% it definitely is. Learn to identify that 20%, and use the other 80% to watch, wait, and keep your powder dry until the right moment. Learning when not to trade is just as important as knowing when to trade. 


Analyse your trading journal

Take a look at your trading journal (you are keeping a trading journal, right?) and work out which are the best and worst performing trades. You may even notice that 20% of your trades generate 80% of your profit. 


See if you can notice a pattern that repeats itself in your most unsuccessful trades, such as a certain time of day or currency pairing that just isn’t working for you. You may even find that your worst trades were those that you made impulsively without any proper planning and research, or were too influenced by your emotions such as greed and fear. 


Next, look at your best results. Do they have any factors in common? Chances are, they are the trades where you were disciplined enough to follow through with your trading strategy and remained completely objective in your decision making process. 


Whatever you find, look for the reasons behind the wins and losses in your track record, and refocus your energies on the techniques that are bringing you the best results. 


80% of trading is about risk management

Forex trading is largely a process of taking managed risks. Even the most experienced of traders accept that only about 50% of their trades will be profitable. The reason why they continue to be successful is that they are able to manage their level of risk to minimise their losses. 


The first step to risk management is to understand your risk tolerance; in other words, how much money are you comfortable with losing on each trade? Most forex traders are risk averse and will only risk between 1 and 3% of their account balance on each trade. Your approach will depend largely on your financial circumstances and personality.


Consider how much spare capital you have at your disposal, your level of trading knowledge and experience, and your temperament. Are you a natural worrier who would be kept awake at night by the thought of potential losses? Or are you someone who is comfortable with a level of uncertainty? How confident are you in your current trading abilities?


The other main risk management strategy is to use stop loss orders. No matter how confident you may be that you have identified a great trading opportunity, the markets are volatile and don’t always move in predictable ways. 


A stop loss order automatically triggers an instruction to sell the currency pair at the market price once a predetermined price is achieved. This provides you with a safety net to mitigate against incurring substantial losses on any one trade, should the market suddenly turn against your favour.


It is important to note that when the stop loss is triggered, it becomes a market order, and is executed at the market price, which may be higher or lower than the stop loss price. It is possible to move your stop loss after your position is open, to protect a good profit margin or to move it out of the loss zone. 


You may not want to set a stop loss on all your trades, but you can use the Pareto principle to identify your least successful 20% of trades and use stop loss orders for these. 


Applying the 80-20 rule to your time management

One of the most effective ways to apply the pareto rule to your trades is by addressing your time management. If it holds true that 20% of our actions account for 80% of the outcomes, then it’s worth examining exactly how you spend your time when trading. 


You may be familiar with the adage that work expands to fill the time available. This is known as Parkinson’s Law, because it was first observed by Cyril Northcote Parkinson in a 1955 essay for The Economist. In essence, it’s the idea that a simple five or ten minute task can take all day if we let it.


When we think that we have plenty of time at our disposal, it is easier to get sidetracked with small and often irrelevant details. We might also take more opportunities to procrastinate. Sometimes, this can be a useful learning experience, but mostly, it’s just an inefficient use of time. 


To test how this theory might apply to you, limit your trading time by a few hours each week, or even each day if you devote yourself full time to trading. You might be surprised at how well you begin to focus on the most important aspects of your trading routine, and spend less time on the least productive tasks.


Note down how spending less time trading affects the outcome of your trades over the course of two weeks or a month. Did your success rate go up or down? You might be surprised to learn that you are getting better results, despite putting in fewer hours. It might be a cliche, but working smarter rather than working harder can really pay off.


Focus on your best performing currency pairs

Finally, this might seem obvious, but if you trade a lot of different currency pairs, it is likely that 20% of them are generating 80% of your profits. Unless you particularly enjoy the challenge of trading minors, it’s best to focus on the strongest currencies.

If you are looking for an instant funding prop firm, please get in touch with us today.

Recent articles


Share:

HOW TO BECOME A MORNING PERSON

How To Become A Morning Person

There are lots of skills you’ll need to develop when first embarking on your career as a forex trader and you are likely to find that you’ll need to make quite a few lifestyle changes at the very beginning if you’re to drive serious success your way.


Working on your analytical skills is a must, of course, as is developing patience, mental resilience and emotional fortitude, anger management, motivation, determination, focus, discipline… the list goes on and on, and you’ll also likely find that the list grows the more you trade.


New and inexperienced traders learn a huge amount about themselves while trading and being able to identify your weaknesses and vulnerable areas, in terms of both your personality and your lifestyle, is important so you know where to focus your attention first. 


It may well be the case that you need to make a few significant changes here and there if you are to enjoy a lucrative career and make it big as a professional trader – so don’t be shy about asking yourself the difficult questions and being strong enough to enact meaningful and long-lasting change.


When it comes to success, whether that’s as a trader or in some other profession, there’s something that all leaders in their chosen fields seem to have in common… and that’s getting up very early in the morning.


The old adage that the early bird catches the worm certainly does seem to ring true and there’s a growing body of research backing this tidy little cliche up.


It seems that being an early riser is associated with all sorts of positive behavioural traits, everything from being more proactive and more productive to being calmer, more relaxed and healthier overall in general… all of which will really help you on your quest to become one of the top traders in the world.


Interestingly, many of the very best investors out there think the best time to trade is between 8am and midday, because this is when the London and New York exchanges overlap and these are generally the busiest markets for forex trades.


This means that you’ll have to get up pretty early if you’re going to take full advantage of the most lucrative trading times and get ahead of the competition. You probably won’t see the success you’re looking for if you roll out of bed at 07:59. 


Winning trades often comes down to state of mind and mental acuity, so getting out of bed far earlier and being proactive with your morning before you even think about trading will likely stand you in excellent stead in your trading career.


So, with that in mind, here are a few strategies you could consider trying out if you are keen to get out of bed at the crack of dawn (or even before that!) without much trouble at all. Which of these will you put into practice first?


Change your inner dialogue


If you’ve been a night owl for a long time, it can be very difficult to change your habits and your way of thinking… and it’s likely that you will find it hard to alter your routine at first. 


A good place to begin is with changing how you talk to yourself and switching your internal dialogue around so that you’re not constantly reaffirming your preference for night-time hours to yourself. Instead of saying to yourself that you’re not a morning person, why not try telling yourself that you’re becoming a morning person?


This may sound like it’s too simple to be effective, but mind over matter can be very powerful and you may well find that by changing your thinking and your inner monologue, you find it easier to enact changes externally as well.


Build incrementally


Your system will probably struggle a little if you suddenly start trying to wake up at 5am without giving it any warning. Build it up bit by bit so you can acclimatise yourself to your new schedule gradually, giving yourself more time to get used to the new way of working and maximising your chances of actually being able to stick to it.


Be consistent with your routine


Having a set bedtime and waking up time will make all the difference to how you feel when it is time for you to get up. Shifting your sleep patterns isn’t easy but the first step towards making real inroads in this regard is to maintain the same sleep and wake up times for prolonged periods. 


Setting an alarm is very useful, of course, but what you’ll likely find is that after a couple of weeks your body wakes you up naturally a few minutes before you’re due to get up… and this is a surefire sign that you’re on the right track.


Have a morning routine


Routine is so important and there are all sorts of benefits associated with it, everything from better sleep and less anxiety to less stress and better mental health overall. Coming up with your own morning routine can help ease yourself into the day and it’s all about finding out what works for you.


This could be anything from washing your face immediately to making a coffee and hitting the gym, or going for a run first thing. Meditation could be another option, while other traders may want to start with some journaling to get them into the swing of it all before they switch the laptop on.


The key to building up a successful routine, no matter what it is, is to make sure that it’s sustainable and something you enjoy, perhaps even something you look forward to. Then you’ll have no problems leaping out of bed, ready to attack the day!


Get ready for bed


Getting ready for bed helps your body get ready for sleep… and this will increase the quality of rest you get, which will help you wake up in the morning more readily. 


Again, your routine will largely depend on who you are as an individual and what you like to do, but it could include drinking a hot beverage and winding down with a book, putting on pyjamas, practising self-care by washing your face and moisturising, staying off your phone and other devices for at least two hours before bed and so on.


Setting boundaries can also be very useful as you don’t want your mind to bounce back to alertness, so perhaps consider putting your phone on Do Not Disturb after 9pm so that you don’t receive any phone calls, texts or other notifications.


Get morning sun


Natural light is incredibly good for us and light exposure can really help you in your quest to become a morning person. Whenever possible, head outside early in the morning and soak up those rays, whether that’s by going for a little stroll with the dog or simply taking your morning cup of coffee outside with bare feet to practise grounding.


Getting a hit of vitamin D early on can help you fight fatigue and boost your mental health, as well as easing any feelings of anxiety and depression you may be experiencing and even helping to improve your sleep patterns and sleep quality.


From a science perspective, morning light has both infrared and blue light wavelengths, which means there is no UV light when you step out first thing in the morning. Think of yourself as a battery and the morning sun as the charger… you can give yourself a big energy surge if you get out and about early in the morning.

What’s more, research suggests that getting rays early in the morning can actually help protect you against UVA and UVB rays later in the day, helping to fortify your skin against potential sun damage… so it’s a real win-win!


Give grounding a go


While you’re out enjoying your morning sun, why don’t you give grounding a try to see if that helps you feel more alert in the early hours? Also known as earthing, the practice involves kicking off your shoes and socks and touching the ground with your feet, something that many believe can have all sorts of positive benefits for the mind, body and soul.


In terms of health, a growing body of research suggests that grounding can help you sleep better, feel less stressed, improve your mood, reduce feelings of depression, boost your heart health, improve circulation… and a whole lot more besides!


What’s great about it is that it can be done wherever you are and you don’t need any specialist equipment to start reaping the benefits. So the next time you’re up early and have a spare 20 minutes, why not give it a go and see if it could make a difference to how you’re feeling at the crack of dawn?

Looking into forex prop firms at the moment? With one of our trading programmes, you can trade where you like, when you like!

Recent articles


Share:

WHY SELF DISCIPLINE IS ESSENTIAL FOR FOREX TRADERS

Why Self-Discipline Is Essential For Forex Traders

Forex trading demands a whole range of skills, from technical analysis to market knowledge and emotional maturity. However, to all this the successful trader needs to add another essential ingredient to make it all work together: discipline. Here’s a closer look at what discipline means in the context of forex trading and how you can develop or improve it.

What does discipline mean in forex trading?

The Collins Dictionary defines discipline as “the quality of being able to behave and work in a controlled way which involves obeying particular rules or standards.” In forex trading, this means being able to develop and stick to your trading strategy, always following your risk management plan, and maintaining an objective viewpoint at all times. 

It may also encompass other factors, such as keeping your learning and market knowledge fresh and current, furthering your technical knowledge, and being able to stick to a daily trading routine. 

Why is discipline considered to be so important in forex trading?

Successful forex trading requires above all a structured approach, so that all your trading decisions are based on the current market conditions, and are aligned with your personal trading strategy and goals. A casual or haphazard approach to trading means that sooner or later you are going to make mistakes that could lead to heavy losses.

Trading requires you to make quick decisions under pressure, and when the stakes are high it takes effort to overcome powerful emotions such as fear, anxiety, and greed. Experienced traders work hard to manage their emotions, and learn not to be swayed too heavily by the prospect of failure or success.

How do you develop discipline as a forex trader?

Self-discipline can be practised by anyone, no matter what their personality type is. It is not an innate trait we are born with, but it is something that can be learnt. Like a muscle, the more we work at it, the stronger it gets. 

At the beginning of your trading career, you will make mistakes and experience a few lows, but the right mental attitude will carry you through to more long-term success. Here are some points that will help you to develop and maintain the right mindset.

Set clear achievable goals

It can be easy to become overwhelmed by the prospect of learning how to be a successful forex trader, and this can lead to a sense of paralysis. Instead of getting bogged down in detail, set yourself a series of clear and realistic goals to work towards. 

Avoid setting numerical targets, such as needing to make a certain amount of profit each month. If you have given up your day job and intend to make your living as a forex trader, you may expect to earn a fixed amount of money each month to replace your salary.

 However, there is no such thing as a steady income in forex trading, and even the best traders will make a variable monthly amount. Chasing numerical targets can lead to poor trading decisions, and is unlikely to yield the best results. Profits are the byproduct of a disciplined trading system, and not a goal to be single mindedly pursued. 

Instead, use the following methods to keep you on the right track.

Set out your trading strategy

A well defined trading strategy is the key to successful forex trading. This should include which signals you will use to enter and exit the market, what your maximum number of trades per day or week will be, and what hours you will be trading each day. You should also decide if you prefer short term trading or long term trading.

Work out your risk tolerance

It is absolutely essential to know how much you can realistically afford to lose on each trade before you begin trading. This may depend on how comfortable you are with risk and how much capital you have at your disposal. You should never expose yourself to damaging losses that would compromise your ability to pay for life’s essentials.

Use a stop loss

Stop losses are a tool that enables you to automatically exit a trade at a specified point below the entry price. They can act as a buffer against volatile and unpredictable market conditions, so if the price action suddenly swings against your expectations, you will be protected from uncontrolled losses.  

This can help to guard against the natural human tendency to hang onto a losing trade in the hope that the situation will turn around, rather than to cut your losses and run. If you think that you have enough presence of mind to decide for yourself when to exit a trade, remember that almost all professional traders use stop losses.

When we are faced with a difficult decision under pressure, most of us will subconsciously follow some kind of cognitive bias. Assuming that you are immune to such human frailties will only put you in a weaker position, because like it or not, all humans experience powerful  emotions and denying them can be dangerous in forex trading. 

When faced with the prospect of making a bigger profit or trying to avoid a loss, even the most stoical of personalities will have a natural tendency to either reach for more or hedge against a losing position. This is a primal evolutionary instinct leftover from the times when it literally meant the difference between starving or surviving. 

A predetermined exit strategy such as a stop loss is based on objective and rational information only, which is ultimately what forex traders should be aiming for at all times. This brings us nicely onto the next point…

Understand forex trading psychology

A major part of your discipline as a forex trader is learning to manage your emotions. As we have already discussed, letting your emotions bias your trading decisions can be potentially disastrous. Some people hold the belief that admitting to their feelings is a weakness, but in fact it can put you in a much more empowering position, in life as well as in forex trading. 

No one is immune to psychological bias, and being able to recognise them in your own thought and behaviour patterns is key to avoiding the trading pitfalls that they can open up. Here are some of the most common biases in forex trading.

Overconfidence bias

This is a very common bias in novice traders who have experienced their first flush of success. After all the hard work of learning the ropes and feeling like a newbie who doesn’t quite know what they are doing, a string of profitable trades can be a huge ego boost. 

There is nothing wrong with taking some time to enjoy your success; after all, if we didn’t allow ourselves to enjoy the fruits of our labour, it would be rather miserable and demotivating. Taking some time to work out what you did right is also important, because it strengthens your trading strategy. 

However, some traders are prone to become too intoxicated by their success, and assume that every future decision will be right. This can lead to a relaxing of discipline and poor trading decisions will be the result. No matter how well you have done, do not be tempted to ease up on the rigours of daily market analysis and strict risk management.

Loss aversion bias

The flip side of overconfidence bias is loss aversion bias. This is when a trader is too conscious of the prospect of loss, and this hampers the ability to pursue profits. For many people, the fear of losing overrides the instinct to make gains, and it can lead to overcautious decisions. 

Forex trading is all about learning to take managed risks, based on daily market research and analysis. It does not pay to be either too cautious or too confident, but to learn how to put your emotions or biases to one side and make objective decisions at every stage.

Keep a regular trading journal

This is one of the most repeated pieces of advice to new forex traders, but it really is one of the most effective tools you can use to develop and improve your trading skills. It does take some discipline to add yet another task onto your daily checklist, especially when you may not notice the immediate benefit. 

By recording what trades you have made and when, and the reasons why you made them, plus any other thoughts or observations you may have at the time, you will have a brilliant resource to refer to in the future. It can help you identify patterns of success, or pinpoint what went wrong if you have a run of poor trades, leading to a stronger strategy going forward.

Guard against your comfort zone

Once you have found your feet in the world of forex trading, and are starting to build up a record of steady profits, it can be tempting to take your foot off the gas for a little while. Be on your guard against settling into a comfort zone, and always push yourself to remain open to new opportunities.

If you are looking for an instant funding prop firm forex, please visit our website today.

Recent articles


Share:

FTUK TRADER SHARES THEIR INSIGHT INTO REACHING LEVEL 2!

FTUK TRADER SHARES THEIR INSIGHT INTO REACHING LEVEL 2!

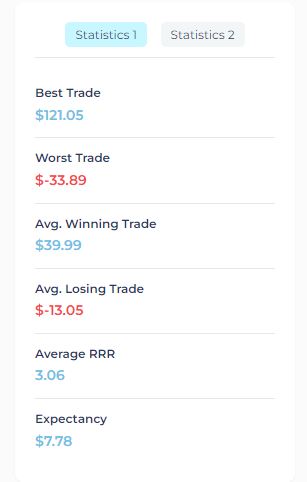
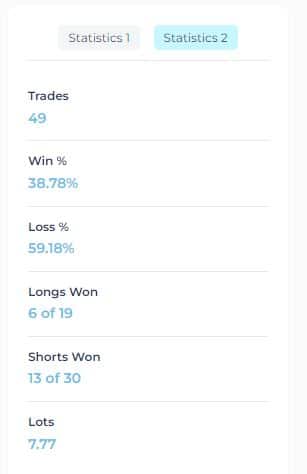
Here we interview Kunal who recently passed his level 1 instant funding account and has gone on to trade level 2 with FTUK. He has show long-term consistency with us with some great results to show for it.

He has had a very positive experience with FTUK and we very much look forward to seeing more positive results with this trader!


Recent articles


Share:

4 BREATHING TECHNIQUES TO HELP YOU DEAL WITH STRESS

4 Breathing Techniques To Help You Deal With Stress

As rewarding as trading can be, there’s also no denying that it can be incredibly stressful, particularly when you first start out with forex, as there’s so much to learn, so much to take in and so much to get to grips with.

It’s entirely understandable if you feel your blood pressure start to rise when you first start trading currency pairs, but it’s essential that you give yourself all the tools and resources you need to help you keep your emotions under control.

As we’ve said before (and as we’ll no doubt say again), emotional management is one of the top skills you’ll need to develop as a trader. Emotional trading is always ill-advised, whether you’re feeling stressed, anxious, sad, happy, angry or something else. 

You need to make your decisions when you’re level-headed and thinking clearly, so you know you’re acting rationally and aren’t being swayed in one direction or another by some underlying urge. Succeed in this endeavour and you’ll likely see more consistent wins over time. Fail and you’ll likely start to see your profits take a hit.

But how do you go about regulating your emotions and how do you stop them from taking charge?

As with anything, it all comes down to practice and making sure that you have all you need at your disposal to help you take a step back, calm down and remain in control, no matter what happens on the trading floor.

To that end, you will likely find that focusing on your breathing can help you centre your mind, calm your nervous system and keep you on the straight and narrow. Here are just a couple of breathing techniques you could try that may well stand you in excellent stead throughout your trading career.

Nasal breathing

Breathing deeply in and out through the nose is an incredibly effective way of reducing feelings of anxiety and you can practise it at any time, no matter what you’re doing, so you’re sure to become an expert at it in no time at all.

Nasal breathing is a more relaxed way of getting the breath you need, helping to lower your blood pressure and keep your heart rate in check, so it could yield all sorts of positive effects for traders, both novice and experienced alike.

It can help stimulate your parasympathetic nervous system, instead of your fight or flight responses, so it keeps you calm even when you’re faced with seriously stressful circumstances… again, essential for traders of all kinds and at all levels.

Of course, we tend to breathe without thinking about it, so you may be breathing through your mouth without even knowing about it. 

The first step to switching to nasal breathing is to become more aware of your breathing patterns, looking out for if your mouth drops open naturally, if your nostrils are regularly blocked and if you wake up regularly with a blocked nose and a dry mouth.

Looking for an exercise to try? What about practising alternate nostril breathing, where you inhale through one nostril and then exhale through the other, using your finger to close the opposing nostril each time. 

This is also a great mindfulness technique since you’ll need to focus quite closely on what you’re doing, helping to clear your mind and making you feel even less stressed and anxious as you breathe.

Belly breathing

Diaphragmatic breathing (also known as belly breathing) is another brilliant way to help keep yourself calm, no matter what’s happening with your trades.

It may be a little trickier than nasal breathing to get to grips with, but the benefits can be extensive once you know what you’re doing. 

Again, you may not necessarily be aware of just how important your diaphragm is for your breathing since everything happens relatively automatically, but this muscle (which can be found at the base of your lungs) actually has a really essential role to play with your breath. 

When you inhale, it tightens and moves downwards to create more space in the chest so your lungs can then expand even further. And when you exhale, the muscle relaxes, moving back up into the chest cavity.

Belly breaths means you can take bigger, deeper breaths, so you’re working to encourage full oxygen exchange, which in turn then helps to slow your heart rate and reduce your blood pressure… which can prove very useful indeed from a trading perspective.

To get started, lie down on the floor or on your bed with your knees bent and a pillow beneath your hand. Place one hand on your chest and the other on your belly, just under the ribcage. 

Breathe in slowly through the nose and direct the air down towards your belly, feeling your hand rise as your belly does. The hand on your chest should remain still – which is how you know you’re doing it right. Practise this a couple of times a day (you can also do it sitting on a chair, if that’s more practical) and you’ll soon get the hang of it.

Bellows breathing

The next time you’re stressed and anxious, pay attention to what happens with your breathing. You’ll probably find that your breaths are shorter, more irregular and more shallow than they are when you’re calm and you’ll probably find that your chest and shoulders come up when you inhale. 

That’s because your sympathetic nervous system has been triggered by something and your fight or flight responses are now in charge.

Focusing on your breathing helps you to calm down, make you feel better and allow you to start thinking more rationally – something that bellows breathing techniques can really help you with.

Also known as Bhastrika, this type of breathing is something you often come across in yoga practice and it’s a popular one because it can help with stress, is energising and can potentially drop your heart rate and blood pressure, all at the same time.

To start, sit up and make sure your shoulders are relaxed. Take a few deep breaths through your nose and fill your belly with as much air as you can each time. Breathing from your diaphragm, quickly and forcefully inhale and exhale through your nose, aiming for ten breaths per cycle.

At the end of each cycle, take a break and breathe normally, then return to your bellows breath and repeat for three cycles. Once you’ve got to grips with the technique, you can start increasing the number of breaths and the number of cycles you are able to do.

Because it’s so energising, you may find that you prefer practising this technique first thing in the morning as a sort of wakeup call to get yourself all pumped up and ready to take on the day.

Humming bee breath

Yogic breathing can really help our physical, emotional and mental health and if you’re keen to put it into practice, the humming bee breath technique could be a great place to start… although you may want to make sure that there’s no one else around if you’re on the shy side, since you’ll be making lots of noise as you do it.

It involves making a humming sound as you breathe out, rather like the noise that a bee would make (hence the name!), and it’s thought that the sound and vibrations can really help release tension, soothe your anxious and stressed mind and help you feel more relaxed as you breathe.

To get started, sit down and make yourself comfortable somewhere, then close your eyes so you can really focus on what you’re doing and aren’t distracted by anything around you. Take a couple of moments to breathe in and out slowly through your nose, identifying any areas of tension in your face and body to encourage them to relax.

Using your index fingers, close off the tragus cartilage or cover your ears with the heels of your hands, then inhale and exhale deeply through the nose while your ears are covered. As you exhale, emit a humming noise – similar to a bee in tone. Repeat for six to ten cycles of breath, focusing on the sound of the breath and the vibration of the hum itself.

The idea is to strike a balance between the hum being strong enough for you to feel it but quiet and gentle enough for it to be relaxing for you. Tune into the vibration and see where you can feel it… hopefully it should be nice and soothing!

Once you’ve finished your cycles of breath, check in with yourself and see how you feel mentally, emotionally and physically. Hopefully, you’ll feel less agitated and stressed, less anxious and better able to tackle the tasks ahead.

Looking for a new funded forex trader program at the moment? We’ve got everything you need right here.

Recent articles


Share:

THE FACTORS THAT SHAPED MODERN FOREX TRADING

The Factors That Shaped Modern Forex Trading

Modern forex trading is now one of the most popular and exciting methods of financial trading in the world, thanks to a liquid market which is easily accessible to anyone with an internet connection and a forex funded account. This is a relatively modern development of course, but the history of forex trading has deep roots. 


The concept of forex trading—that is, exchanging foreign currencies—can be traced back for centuries. The current market is shaped by significant events from the past, and it is useful for any forex trader to understand how these occurred, because history tends to repeat itself. Here’s a look at how it all began.


The early bartering system

It could be argued that modern forex trading began when prehistoric cave dwellers began to exchange animal skins for meat or flint tools. In fact, some societies in the world still use the bartering of goods and services as a means for survival, in place of money. However, using currency makes the whole process faster and (usually) fairer.


The first coins and notes

The world’s oldest known coins have been discovered in Guanzhuang in Henan Province, China, according to Investopedia. Archaeologists from the State University of Zhengzhou have dated the coins back to 640 BC. Records of the use of metal coins can also be found in the works of Greek poets from the 6th century BC.


It is thought that the Romans were the first to establish a centralised system for minting money, which was operated by the government. This is not so different from the centralised banking systems which still dominate today. 


It is thought that the first system of using paper notes instead of money was introduced during the 7th century BC in China. This was probably a result of the inconvenience of tradesmen having to undertake long journeys weighed down by bags of heavy metal coins. 


Apparently, early Chinese banknotes were printed with the blunt warning: “Those who are counterfeiting will be beheaded.” Of course, counterfeit bank notes are still a serious problem today, although the penalties are not usually quite so barbarous. By the Middle Ages, lower value coins made from copper rather than silver or gold were minted.


It took until the 16th century for paper money to become widely used throughout Europe and North America. This opened the gateway to increased international trade, as the whole process became quicker and more fluid. 


It also led to the beginnings of the first foreign exchange market, as banks and governments were able to buy currencies from other nations. 


The Gold Standard

The next major development in the history of financial trading was the adoption of the gold standard. This was a guarantee that a government would redeem an amount of paper money for its value in gold. By pegging a currency’s value to gold, this created a system where an economic unit was based on a fixed quantity of gold. 


Gold has been considered a precious metal since the earliest ages, because of its unique qualities of strength, malleability, density, and limited resources. It has always been used as a decorative metal and to made sacred artefacts, and it was used to make coins from about 700 BC onwards. 


The gold rushes and pillages in the New World in the 15th and 16th centuries intensified the gold trade wars, until eventually the Gold Standard was introduced as the basis for the international monetary system during the 1870s. In the US, a united national currency pegged to the value of silver and gold had already been in operation for almost a century.


However, England was the first country to officially adopt the Gold Standard in 1821. The international Gold Standard was consequently adopted by all the major economies by the beginning of the 20th century. This system flourished until the outbreak of WWI in 1914, when European countries became mired in war debt.


The supply of gold could no longer keep up with the growth of the global economy, and the use of the Gold Standard became unsustainable. Smaller nations began holding the US dollar and the Great British Pound as their reserve currencies instead of gold, thus reducing its fluidity even further.


To this day, the US dollar is the world’s biggest reserve currency, and represents the least exchange risk. This is why beginner forex traders, as well as many experienced ones, almost always include the US dollar as one of their currency pairs. 


Even those traders who avoid the USD still keep a close eye on its movements in the market, because what is affecting the value of the USD has a ripple effect on the direction of the whole forex market.


The Bretton Woods Agreement

The next major development occurred in 1944, with the historic Bretton Woods Agreement. This refers to the outcome of the United Nations Monetary and Financial Conference held in Bretton Woods, New Hampshire, which was held in 1944. 


The conference was attended by delegates from 44 countries, with the aim of agreeing a workable foreign exchange system to promote global economic growth. The International Monetary Fund (IMF) and the World Bank, still two major global financial institutions today, were also created at the meeting, outlasting the agreement itself.


The key principles of the Bretton Woods Agreement had already been carefully prepared by the British economist John Maynard Keynes and the US Chief Economist, Harry Dexter White. The basic operating principle of the system pegged the US dollar to the price of gold, and all other currencies within the system were pegged to the value of the USD.


The idea behind the Bretton Woods Agreement was to help create a stable international currency exchange rate, which would facilitate more frequent and profitable international trade, and promote good trading relationships between countries. This worked well for a time, but by the early 1970s, the US gold supply had become depleted.


The Bretton Woods Agreement was abolished in 1973, because it was no longer adequate to support rapidly growing economies. However, the IMF and the World Bank still play an important role in supporting the development and functioning of the world’s emerging  economies. 


Today, the forex markets are mostly comprised of free-floating currencies which are subject to the pressures of supply and demand. However, central banks still have a means of influencing the forex markets, through the control of interest rates. 


That’s why it’s important for forex traders to follow the economic news, especially for any data releases involving interest rate rises or falls in the major economies. Rising US interest rates will have an influence throughout the entire forex market, because it will affect the value of the dollar, which is the most widely traded currency in the world. 


The Plaza Accord

By the 1980s, it was recognised that the strength of the dollar in relation to other currencies was stifling the economic growth of other nations. Therefore, the G5 group of the world’s leading economies, including Great Britain, France, West Germany, Japan, and the US, agreed to deliberately appreciate other currencies against the dollar.


This agreement was reached at a meeting at the Plaza Hotel in New York, and was therefore known as the Plaza Accord. The result was much greater fluctuation in the forex markets, which made for ideal trading conditions for the sharp-eyed forex trader, because the potential to make big profits was created by sharp upturns and downturns in price.


The creation of the Euro

The next significant event was the agreement between European Union nations in 1992, known as the Maastricht Treaty, to establish a major new currency. This led to the birth of the Euro in 1999, with 11 member EU countries adopting it as their currency. It has since grown to be one of the world’s major currencies, used by 19 EU countries.


The advance of the internet

The next major advancement of forex trading was brought about by the internet. Until the 1990s, only large banks and other financial institutions could access the forex markets, but the advance of the world wide web changed all this. 


Information which once involved a series of international phone calls and a whole team of traders could now be retrieved in seconds by a simple internet search engine query. 


At the same time, the globalisation of the world economy began to flourish as the Berlin wall came down and the Soviet Union dissolved. This led to a huge expansion in forex trading, as individuals as well as banks and merchants entered the markets. 


Today, anyone can open a forex trading account through an online broker, even if they have only a modest amount of capital to invest. High leverage means that there is potential for skilled traders to make good and consistent profits, and some individuals even make forex trading their full-time career.


More than $5 trillion are traded every day on the forex markets, with endless opportunities for the well-informed trader to make profits. It does take commitment and hard work, but learning to trade forex is certainly an exciting and potentially very lucrative venture. 

Recent articles


Share:

CONFIDENCE VS ARROGANCE IN FOREX TRADING

Confidence V Arrogance in Forex Trading

The world of forex trading is fast moving and competitive, and it takes a certain amount of confidence to set out your stall and take part. Along the way, almost all new traders experience their fair share of obstacles and setbacks, which is all part of the learning process. 


Those with the determination to see it through will soon find a strategy that works for them, and will begin to taste the heady cocktail of excitement, success, and financial rewards that instant forex funding can offer. However, a run of good trades can sometimes lead to arrogance, and this is never a good way to approach the markets!


Overconfidence can be a very dangerous trait in the world of forex, because it can lead you to take unmanaged risks without enough objective evidence that the risk is worth the potential reward. In the worst case scenario, you could end up suffering damaging uncontrolled losses that leave you in serious financial straits.


On the other hand, an over cautious and timid approach to your forex trading is unlikely to bring you to a consistent level of profitability that makes it worth staying in the game. So how do you find that balance between being confident in your trading, and being hubristic and overconfident? Here are some points to bear in mind.


Recognise the difference between arrogance and self confidence

Before getting into more technical points, it’s worth spending some time thinking about the difference between arrogance and self confidence. Hubristic individuals who display high levels of assurance can sometimes be perceived as self-confident, and maybe they are. However, it is possible to be self-confident without hubris or excessive pride.


Arrogant traders believe that they are too talented or knowledgeable to fail, or even that they have some sort of magic touch. Unfortunately, all too often, this level of self belief is not justified by any objective evidence. Anyone can have a string of lucky breaks that might make them fall into this trap, but experienced traders will all tell you that luck runs out.


The truly self-confident trader needs to have a high degree of faith in their own abilities, but the difference between them and the arrogant is that they have good reasons to be confident. In other words, they have evidence that their skills and knowledge are based on sound and objective research and market knowledge. 


Being self confident doesn’t mean denying all possibility that you might fail: in fact, it means the opposite. Real confidence goes hand in hand with humility, because it is impossible for even the most experienced trader to avoid risk and loss in forex trading. Good traders base their strategy mainly around risk management.


They are also always willing to listen to the advice and opinions of others, no matter how sharp witted or well educated they may be themselves. A good forex trader knows that they don’t know everything, and there is always something new to learn, or a different take on a familiar topic. 


This doesn’t mean that they are willing to abandon their own strategy and be pulled and pushed around by every piece of advice that they come across, but rather that they have developed the independence of mind to objectively analyse new information, and put their own biases to one side. 


The hubristic or arrogant trader will almost always push away advice without giving it any well balanced consideration, because they believe that they know best. This can lead to a narrow approach to trading decisions, and sooner or later the result will be less profitable trades or losses. A previous track record of wins does not guarantee future success.


The dangers of reckless pride has been a theme for artists and writers for centuries, all the way back to the scribes of Ancient Greece. The word ‘hubris’ (meaning excessive pride or self-confidence) comes from the Greek goddess Hybris, who was the personification of arrogance, conceit, and lack of regard for others. 


Literature is full of examples of humbled heroes or heroines who fell to earth, quite literally in the case of Icarus from Greek mythology, who flew too close to the sun and melted the wax in his wings, despite being warned of the danger. It is a parable about the importance of humility which is very pertinent to forex trading. 


How to develop real self-confidence as a forex trader

One less discussed aspect of the tragedy of Icarus is that he was also warned not to fly too close to the sea, lest his feathered wings get wet and drag him down. This could be a parable for being over cautious, in life as in forex trading. The confident trader is always vigilant that they are flying well above the sea but not too close to the sun.


In less abstract terms, this means that their trading strategy is based on a good understanding of the way the forex markets work, some sound application of technical analysis, and knowing their risk tolerance. All this is underpinned by the ability to detach their trading decisions from their emotions.


This can sound like a lot to take on board, and it does take some time and discipline to make everything fall into place. There are no real substitutions for commitment and hard work when it comes to developing great trading skills. However, as with any overwhelming task, the best approach is to break it down into a series of smaller tasks, so let’s do just that!


Figuring out your risk tolerance

Before you even think about making your first live trade, you must first work out your risk tolerance. This means working out the maximum amount of money you can afford to lose on each trade and setting well defined boundaries. This way, you will always protect yourself from the kind of damaging losses that would affect your ability to pay for life’s essentials.


You don’t need large amounts of capital to open a forex account, because there is high leverage available, but this carries the risk of uncontrolled losses. Therefore, you should always trade with a 1 or 2% margin at the most, at least until you have a lot more experience. 


Read up on market analysis

Knowledge is power, and the more background knowledge you have about forex trading, the more quietly self-confident you will feel. However, don’t feel intimidated or inadequate if you don’t have a degree in macroeconomics. It’s a huge topic, and no one can know everything. In fact, bringing too much into the mix can overcomplicate your strategy. 


One of the best approaches is to learn about the main factors that influence the markets, such as differentials in interest rates, unemployment rates, and GDP of the countries whose currency values you are going to be trading. 


Most new traders focus on a few of the major currency pairs, such as the US dollar, the Euro, the Great British Pound, and the Japanese Yen. Even if you do not intend to trade with the USD, bear in mind that it is the world’s largest currency, and what affects its value tends to cause a ripple effect throughout the whole forex market. 


Learn some technical analysis skills

To be a confident trader, you should understand the basic concepts of technical analysis such as how to read line charts and trend lines. Once you have figured out which type of analysis works best for you, remain consistent in your approach rather than chopping and changing at every twist in the road. 


Develop a daily trading routine

Planning out each day, so that you know what times you will be trading and what tasks you need to accomplish during each session can help you to feel more in control. It also mitigates against the risk of human error, because you can tick each task off your checklist as you go along. 


Avoid revenge trading at all costs

Some people react badly when their confidence is shaken or their pride is wounded. A common pitfall is to ‘revenge trade’ after a painful loss, in an attempt to make up for lost funds or lost bragging rights. However, this is likely to lead to ill judged decisions, which are clouded by your emotions rather than based on objective analysis. 


Instead, it is always best to step away and have a cooling off period after a bad result. Take a look at your reasons for making the trade, and try to work out what went wrong. How could you approach it differently? Knowing when not to make a trade is just as important as knowing the right time.


Above all, stay humble

If it’s all starting to come together and you are raking in steady profits, remember that this is not the moment to let your guard down. Sure, enjoy your success and reflect on what you have got right, but remember that you are never bigger than the markets. To remain competitive as a trader you need a constant system of checks and balances.

Recent articles


Share: